Kansas City Metro
Overland Park · Olathe · Kansas City
Hail, finished-basement water losses and HOA rules about shingles and siding. Higher metro labor rates that statewide price lists miss.
Independent claim appraisal · All 105 counties
The insurer accepted your claim, but the check won’t cover the repair. A Kansas Insurance Appraiser builds an independent, line-by-line valuation and takes it through the appraisal process written into your policy.
01 Covered, but underpaid
Most short claims aren’t denied. They’re just short: a few slopes approved on a roof the hail hit everywhere, siding patched where it can’t be matched, gutters and screens left off, an old roof pushed onto a payment schedule with the wrong age. A Kansas Insurance Appraiser exists for that gap between “covered” and “paid in full.”
02 Services
Twelve services, one goal: a valuation of your loss that holds up. Start with an estimate review, or bring us in once appraisal has been demanded.
 01
We act as the appraiser you name when the appraisal provision in your policy is invoked.
Learn more 02
Houses, townhomes and condo units where the carrier’s estimate leaves out real repair costs.
Learn more 03
Retail, office, warehouse, multifamily, church and association properties with complex losses.
Learn more04Hail is the Kansas claim. We document every slope, vent, gutter and screen the storm touched.
Learn more 05
Tornado, derecho and straight-line wind losses, from lifted shingles to total destruction.
Learn more 06
Ice-loaded limbs, collapsed gutters, ice dams and burst pipes after a hard Kansas freeze.
Learn more 07
Sudden leaks, supply-line failures, roof leaks and sewer backups with incomplete scopes.
Learn more 08
Structure fires, smoke and soot migration, and the contents inventories that follow.
Learn more 09
Wind-driven prairie fires that burn homes, fences, barns and equipment sheds across rural Kansas.
Learn more03 The process
The appraisal clause turns an open-ended argument into a defined process with a binding result. Here is the path from first call to signed award.
We read your policy, the insurer’s estimate and your photos, then tell you whether appraisal makes sense.
We inspect and measure the property and build a line-item estimate priced for your part of Kansas.
Appraisal is demanded in writing and you name a Kansas Insurance Appraiser as your appraiser on time.
We work through the differences with the insurer’s appraiser, line by line, with photos and measurements.
Open items go to a neutral umpire. Two signatures set the amount of loss and payment follows the policy.
04 Statewide
Hail in Wichita, tornadoes in Topeka, ice in Lawrence, prairie fire near Hays. A Kansas Insurance Appraiser has to know how each region’s weather shows up on a roof, and in an estimate.
Overland Park · Olathe · Kansas City
Hail, finished-basement water losses and HOA rules about shingles and siding. Higher metro labor rates that statewide price lists miss.
Topeka · Lawrence · Manhattan
Tornado history from Topeka to Manhattan, historic homes with plaster and wood siding, limestone buildings and university rentals.
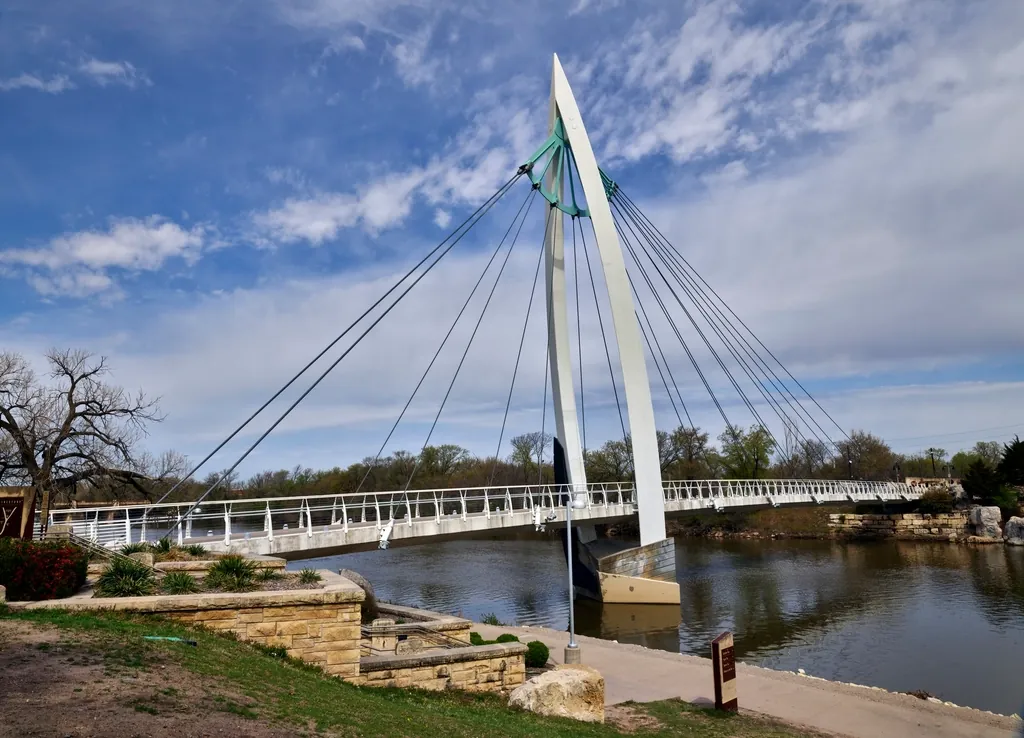
Wichita · Hutchinson · Andover
One of the busiest hail corridors in the country, plus tornado and grass fire losses. Big storms mean thousands of claims at once.
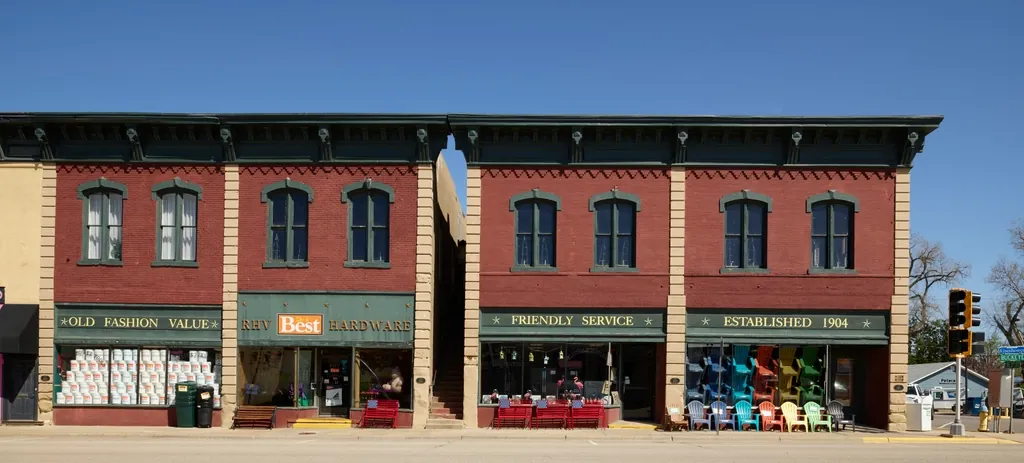
Salina · Abilene · Concordia
Hail and straight-line wind on homes, commercial buildings along the interstates and farmsteads across rolling country.
Hays · Colby · Goodland
Limestone homes, metal farm buildings and wind-driven fires such as the December 2021 Four County Fire.
Dodge City · Garden City · Liberal
Large hail, tornadoes, blowing dust and prairie fire, with contractor travel adding real cost to repairs.
05 Quick check
Type in the two numbers you already have. If the difference is large, a conversation with a Kansas Insurance Appraiser makes sense. If it’s small, a documented supplement may close it faster and cheaper.
The full appraisal payoff projector adds appraiser and umpire fees so you see a realistic net figure. Example numbers are illustrative.
06 Free calculators
Run the numbers before you pick up the phone. Every calculator works in your browser and nothing you type is stored or sent.
Open all calculators Calculator
Size the dispute, test where an award might land and subtract appraiser and umpire fees.
 Calculator
Split a replacement cost claim into the first ACV check and the depreciation released after repairs.
 Calculator
Turn a footprint and pitch into true roof squares, bundles and a rough replacement figure.
 Calculator
See a 1% or 2% wind/hail deductible in real dollars and what a hail claim would actually pay.
 Planner
Map notice, proof of loss, holdback and suit dates from your date of loss, then export them.
 Checklist
Answer 12 yes/no questions to score your claim file and get a to-do list before you demand appraisal.
 Calculator
See how a roof payment schedule tied to roof age cuts a Kansas hail payout, and by how much.
07 Cities
We serve every county in the state. These are the cities where our claims come from most, each with its own storms, housing and repair costs.
08 Before you demand
Appraisal values a covered loss. If the insurer denied the claim or cited an exclusion, talk to a Kansas attorney before anything else.
Fees come out of the increase. A gap of a few hundred dollars rarely justifies appraisal; a missed roof replacement often does.
Both line-item estimates, dated photos and your policy. The appraisal prep scorecard shows what is missing.
09 FAQ
Straight answers about how appraisal works, what it costs and when it is the wrong move.
We value property damage when you and your insurer agree a loss is covered but disagree on the cost. As your appointed appraiser we inspect, build an independent line-item estimate, work with the insurer’s appraiser and, if needed, present open items to a neutral umpire.
No. A public adjuster manages and negotiates the whole claim. An appraiser works inside the policy’s appraisal clause on one question, the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.
When coverage is accepted, you have the insurer’s estimate and the gap between it and your contractor’s number is meaningful, generally more than about 10% or several thousand dollars.
On the amount of loss, yes, once any two of the three panel members sign it. That is why documentation matters before appraisal is demanded.
Each side pays its own appraiser and usually half of the umpire. We put our fee in writing before any work starts, and the first conversation is free.
Yes. We work in all 105 Kansas counties, including Wichita, the Kansas City suburbs, Topeka, Lawrence, Manhattan, Salina, Hays, Dodge City and Garden City.
10 Guides
Practical guides on hail claims, roof schedules, tornado documentation and choosing an umpire.
Three policy features now decide many Kansas hail payouts. Here is how each works and how appraisal fits around them.
Appraisal handles the amount of loss. Some disputes need a lawyer. Here is a careful, general look at the line between them in Kansas.
What to photograph, measure and save after a tornado or derecho so the amount of loss can be valued fully.
11 Start here
Tell us what happened and what the insurer offered. We’ll review it and give you a straight answer on whether appraisal is worth pursuing, with no pressure and no obligation.
